The numbers tell a striking story: artificial intelligence is quietly becoming a critical tool inside nuclear power plants, and the market for it is expanding at a pace that demands attention. A new report from The Business Research Company projects the sector will more than quadruple in value by 2030, even as the competitive landscape remains surprisingly fragmented.
Artificial Intelligence (AI) In Nuclear Energy Analysis
Artificial Intelligence (AI) In Nuclear Energy Industry
Also worth a look: Columvi market forecast: Roche’s lymphoma drug on track to top $2B by 2030 and Starting Point wins platinum honor for doubling employer child care dollars.
The Business Research Company’s Artificial Intelligence (AI) In Nuclear Energy Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 27, 2026 /EINPresswire.com/ — Artificial intelligence is no longer a peripheral experiment in the nuclear energy sector; it is becoming central to how plants run more safely and efficiently. From optimizing reactor performance to strengthening safety protocols, AI tools are increasingly woven into daily operations. This analysis digs into the AI in nuclear energy market’s projected size, dominant regions, key segments, growth catalysts, and the competitive dynamics shaping its trajectory toward 2030.
Market Size and Forecast for Artificial Intelligence in Nuclear Energy Market
The market for AI in nuclear energy is on track to surpass $9 billion by 2030. To put that in perspective, the broader Utilities industry is itself expected to reach a staggering $9,379 billion by the same year, meaning this specialized AI segment accounts for roughly 0.1% of that enormous total. While still a niche, the rapid growth signals a significant shift toward technology-driven solutions in nuclear power.
Request A Free Sample Of The Artificial Intelligence (AI) In Nuclear Energy Market Report
https://thebusinessresearchcompany.com/sample_request?id=30841&type=smp&name=Artificial%20Intelligence%20%28AI%29%20In%20Nuclear%20Energy%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
North America’s Dominance in the AI in Nuclear Energy Market by 2030
Looking ahead to 2030, North America is forecast to lead the global market, with an estimated value of $4 billion. This represents a significant leap from the $2 billion projected for 2025, translating to a compound annual growth rate (CAGR) of 19%. Several factors are fueling this expansion, including the integration of AI-driven digital control systems in existing plants, heightened investment in advanced reactor concepts like small modular reactors (SMRs), increased government backing for nuclear innovation, the growing application of digital twin technologies for plant optimization, and deeper collaborations between AI firms and nuclear operators focused on improving reliability and efficiency.
United States To Lead as the Largest Country Market in 2030
Within North America, the United States is projected to be the single largest market, valued at $3 billion by 2030. That forecast marks a climb from $1 billion in 2025, again reflecting a 19% CAGR. The anticipated growth is tied to the modernization of an aging nuclear fleet, the adoption of AI-powered autonomous inspection and diagnostic tools, substantial public and private investment in next-generation nuclear tech, a growing need for real-time operational data to boost plant performance, and the presence of major AI and nuclear technology firms spearheading digital transformation.
Access The Detailed Artificial Intelligence (AI) In Nuclear Energy Market Report Here
https://thebusinessresearchcompany.com/report/artificial-intelligence-ai-in-nuclear-energy-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Dominant Component Segment in the AI in Nuclear Energy Market
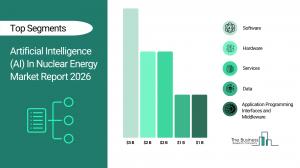
Breaking the market down by component, software is expected to be the largest segment, capturing a 38% share of the total, or approximately $3 billion in 2030. The surge in software demand is driven by the adoption of AI-based analytics platforms for optimizing reactor performance, a rising need for predictive maintenance and asset lifecycle management tools, the expanding use of simulation and digital twin technology for planning, better integration of intelligent decision-support systems for plant operators, and continuous improvements in AI algorithms that enhance automation, efficiency, and regulatory compliance.
Key Deployment and Technology Segments in the AI Nuclear Market
The market is structured by deployment mode into cloud-based and on-premises solutions. On the technology front, the spectrum includes machine learning, deep learning, computer vision, natural language processing, and robotics and automation, alongside other AI-related technologies. These different categories illustrate the varied ways AI can be applied within nuclear settings.
Application and End-User Categories Shaping AI Adoption
From an application standpoint, the market spans asset management and predictive maintenance, reactor operation and control, fuel management and waste reduction, safety and security monitoring, radiation monitoring and dose management, and supply chain and project management. The end users of these AI solutions are diverse, ranging from nuclear power utilities and operators to engineering, procurement, and construction (EPC) firms, original equipment manufacturers (OEMs) and vendors, regulatory bodies, research institutions, national laboratories, and third-party inspectors and service providers.
Anticipated Growth Rate for the AI in Nuclear Energy Market to 2030
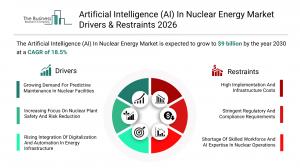
The overall market is forecast to grow at a compound annual growth rate (CAGR) of 19% through 2030, indicating robust and sustained demand for AI-driven solutions in the nuclear field.
Main Factors Propelling Growth in the AI in Nuclear Energy Market
A key driver is the growing demand for predictive maintenance in nuclear facilities. Operators are turning to AI-powered analytics to monitor equipment health, forecast when maintenance is needed, and optimize schedules to prevent critical failures. This approach helps improve plant availability, reduces operational disruptions, and cuts lifecycle maintenance costs, prompting utilities to invest in intelligent monitoring systems. These predictive maintenance efforts are expected to contribute roughly 1.5% of annual market growth.
Another major factor is the increased focus on nuclear plant safety and risk management. AI technologies allow for continuous monitoring of reactor conditions, automatic detection of anomalies, and faster incident response through advanced data analytics and intelligent decision support. Stricter regulatory requirements and a strong emphasis on operational resilience are driving adoption of AI-enabled safety and diagnostic tools, a trend expected to add about 1.2% to annual market growth.
Role of Digitalization and Automation in Advancing AI in Nuclear Energy
The broader push toward digitalization and automation in energy infrastructure is also a vital catalyst. Nuclear plants are increasingly relying on interconnected digital systems that combine AI, automation, and advanced analytics to streamline operations and optimize resource use. Intelligent automation improves process control, offers better operational visibility, and enables faster performance gains in complex nuclear environments. As the energy sector accelerates its digital transformation, the use of AI-powered platforms for nuclear infrastructure is expected to rise significantly, contributing roughly 0.8% in annual growth.
Key Market Opportunities Across Components in the AI Nuclear Sector
Substantial growth opportunities are emerging across various segments, including software, hardware, services, data, and application programming interfaces (APIs) and middleware. Together, these areas are projected to generate over $5.4 billion in market value by 2030. This growth is underpinned by the increasing use of intelligent plant management platforms, wider deployment of advanced data analytics, rising investments in digital modernization projects, growing demand for secure AI integration in critical infrastructure, and continuous innovation in automation technologies. These trends align with the nuclear industry’s broader goals of improving efficiency, enhancing resilience, and accelerating digital transformation.
Projected Expansion Breakdown for AI Components from 2025 to 2030
Between 2025 and 2030, the software segment is expected to grow by $2 billion, while hardware, services, and data markets are each projected to expand by $1 billion. The APIs and middleware segment is forecast to increase by $0.4 billion. Collectively, these expansions underscore the diverse technological investments shaping the AI in nuclear energy market.
Competitive Environment and Industry Leaders in AI for Nuclear Energy
The market features a mix of global technology giants, nuclear engineering firms, and specialized AI solution providers. These companies are concentrating on AI-driven reactor monitoring, predictive maintenance solutions, autonomous plant operations, digital twin technologies, and advanced data analytics to boost nuclear facility performance. Their priorities include ensuring operational reliability, regulatory compliance, cybersecurity, real-time decision support, and optimizing nuclear power generation. Understanding this competitive landscape is essential for stakeholders looking to seize growth opportunities and drive innovation in AI-enabled nuclear energy applications.
Top Market Leader in AI Nuclear Technology
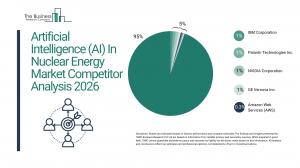
IBM Corporation emerged as the leading sales entity in 2025, holding a 1% market share. IBM’s AI and hybrid cloud portfolio offers advanced platforms for predictive analytics, digital twin modeling, and data management that support improved reactor performance, asset reliability, operational intelligence, and risk-informed decision-making across nuclear power plants.
Important Players Contributing to the AI in Nuclear Energy Market
Key companies active in this space include IBM Corporation, Palantir Technologies Inc., NVIDIA Corporation, GE Vernova Inc., Amazon Web Services (AWS), Siemens Energy AG, Honeywell International Inc., Hitachi Ltd., Asea Brown Boveri Ltd., Mitsubishi Heavy Industries Ltd., Toshiba Corporation, TerraPower LLC., X-energy LLC., NuScale Power Corporation, Framatome SAS, BWX Technologies Inc., Cameco Corporation, Jacobs Solutions Inc., Mirion Technologies Inc., Kinectrics Inc., Assystem S.A., Veolia Nuclear Solutions, Microsoft Corporation, and Rosatom State Atomic Energy Corporation.
Market Fragmentation and Share Distribution in AI for Nuclear Energy
The market remains highly fragmented, with the top ten companies accounting for just 5% of total revenue in 2025. This fragmentation reflects the complexity of AI adoption in nuclear operations and the specialized expertise required to meet regulatory and operational demands. Leading firms such as IBM, Palantir, NVIDIA, GE Vernova, AWS, Siemens Energy, Honeywell, Hitachi, ABB, and Mitsubishi Heavy Industries hold notable shares through their advanced AI platforms, computing capabilities, industrial automation expertise, and established relationships within the nuclear sector. As AI adoption grows for intelligent reactor management, predictive asset maintenance, autonomous monitoring, and safety optimization, these companies are well-positioned to strengthen their market presence through innovation and strategic collaborations.
Key Raw Material Providers Supporting AI Technologies in Nuclear Energy
Major suppliers of raw materials essential for AI hardware components include Taiwan Semiconductor Manufacturing Company, Samsung Electronics Co. Ltd., SK hynix Inc., Micron Technology Inc., Intel Corporation, Advanced Micro Devices Inc., Broadcom Inc., Marvell Technology Inc., GlobalFoundries Inc., Synopsys Inc., Cadence Design Systems Inc., Arm Holdings plc, ASML Holding N.V., KLA Corporation, Applied Materials Inc., Lam Research Corporation, Tokyo Electron Ltd., Keysight Technologies Inc., and Teledyne Technologies Incorporated.
Leading Distributors and Wholesalers in the AI Nuclear Market
Prominent wholesalers and distributors serving the AI in nuclear energy market include Arrow Electronics Inc., TD SYNNEX Corporation, Avnet Inc., WESCO International Inc., Future Electronics Inc., Ingram Micro Holding Corporation, Richardson Electronics Ltd., RS Group plc, Mouser Electronics Inc., DigiKey Electronics, Farnell, Rutronik Elektronische Bauelemente GmbH, Macnica Holdings Inc., Insight Enterprises Inc., Computacenter plc, Redington Limited, Crayon Group Holding ASA, SHI International Corp., and Exclusive Networks SA.
Primary End Users of AI Applications in Nuclear Energy
The main end users deploying AI solutions in nuclear energy encompass utilities and operators like Électricité de France, Constellation Energy Corporation, Duke Energy Corporation, Ontario Power Generation Inc., Bruce Power L.P., Tennessee Valley Authority, Exelon Generation; as well as international entities such as Korea Hydro & Nuclear Power Co. Ltd., China National Nuclear Corporation, China General Nuclear Power Group, Emirates Nuclear Energy Corporation, Fortum Corporation, ČEZ Group, Kansai Electric Power Company Inc., Tokyo Electric Power Company Holdings Inc., Nuclear Power Corporation of India Limited, and Energoatom.
Competitive Trends Shaping AI Development in Nuclear Applications
One notable trend transforming the AI in nuclear energy market is the rise of nuclear-focused large language models (LLMs). These models enhance technical knowledge management, improve regulatory compliance, and support operational decision-making across nuclear facilities. For example, in May 2024, NuclearN.ai launched SPARK-mini, the first open-access LLM developed specifically for the nuclear power industry. Its specialized training, secure on-premises deployment, and integration with regulatory and technical documentation enable accurate information retrieval, streamlined document preparation, and AI-assisted decision support for nuclear operators and service providers.
Strategies Adopted by Market Leaders to Gain Competitive Advantage
Companies in this sector are adopting various strategies to maintain leadership, including:
– Deploying AI-powered predictive maintenance systems to improve nuclear asset reliability
– Integrating digital twin technologies that enhance reactor performance optimization
– Forming strategic partnerships that accelerate AI innovation within nuclear energy operations
– Developing nuclear-specific large language models to provide intelligent decision support
– Implementing cloud-based AI platforms that strengthen real-time monitoring and analytics of nuclear plants
These initiatives collectively aim to drive efficiency, safety, and innovation within the evolving AI landscape of nuclear energy.
What’s new in our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel dashboards
• Market hotspots infographics
• Key technologies and future trends
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
Visit us on social media:
LinkedIn
Facebook
X
Why it matters: The projected 19% annual growth in AI for nuclear energy signals a fundamental shift in how one of the world’s most safety-critical industries will operate in the coming decade. With North America and the US leading the charge, this market’s evolution will likely shape global energy policy, infrastructure investment, and the competitive dynamics between established tech giants and specialized nuclear startups. The fragmentation of the market, where even the leader holds just 1%, suggests significant room for consolidation and innovation ahead.